Financial Aid: The Smart Family's Playbook for College Costs
Financial aid can cover most of a college bill—or barely dent it. Here's how FAFSA, grants, scholarships, loans, and appeals really work in practice.
What Financial Aid Actually Is
Financial aid is any money that reduces what your family pays for college. It comes in four forms, and the mix matters more than the total: grants (free money, typically need-based), scholarships (free money, typically merit, athletic, or talent-based), work-study (a part-time campus or community job funded with federal dollars), and loans (money you repay with interest). A $40,000 package that is 80% loans is not the same as a $30,000 package that is 80% grants — even though the first number looks better in a brochure.
There is also a distinction students often miss: need-based aid depends on your family's finances, while merit aid depends on grades, test scores, essays, auditions, or portfolios. Many private colleges blend both, which is why two students with identical household incomes can receive wildly different offers.
The FAFSA Is the Master Key
The Free Application for Federal Student Aid unlocks federal grants, federal work-study, and federal student loans — and most colleges use it to distribute their own institutional aid as well. It is always free at studentaid.gov. Anyone who offers to file it for a fee is selling you a form you can submit yourself in under an hour.
Two structural things changed when the FAFSA Simplification Act took effect. First, the Expected Family Contribution was replaced by the Student Aid Index (SAI), which can now be negative — down to roughly –1,500 — letting colleges recognize the most financially strained applicants more precisely. Second, the old sibling discount is gone. Having two children enrolled at once no longer divides the family contribution; it is now recorded as information, not as a discount.
Also note the CSS Profile, used by a few hundred mostly private colleges for their own aid awards. It asks for far more detail than the FAFSA, including home equity, business assets, and noncustodial parent finances. If any school on your list requires it, treat it as a second, separate deadline.
How Need Is Calculated
The arithmetic is simpler than the paperwork suggests:
Cost of Attendance − Student Aid Index = Financial Need
Cost of attendance includes tuition, fees, housing, food, books, transportation, and a modest personal allowance. A lower SAI signals greater need. Once you file, the school builds a package to meet some or all of that need. Very few colleges meet 100% of need — and even those frequently fill the final gap with loans or work-study rather than grants.
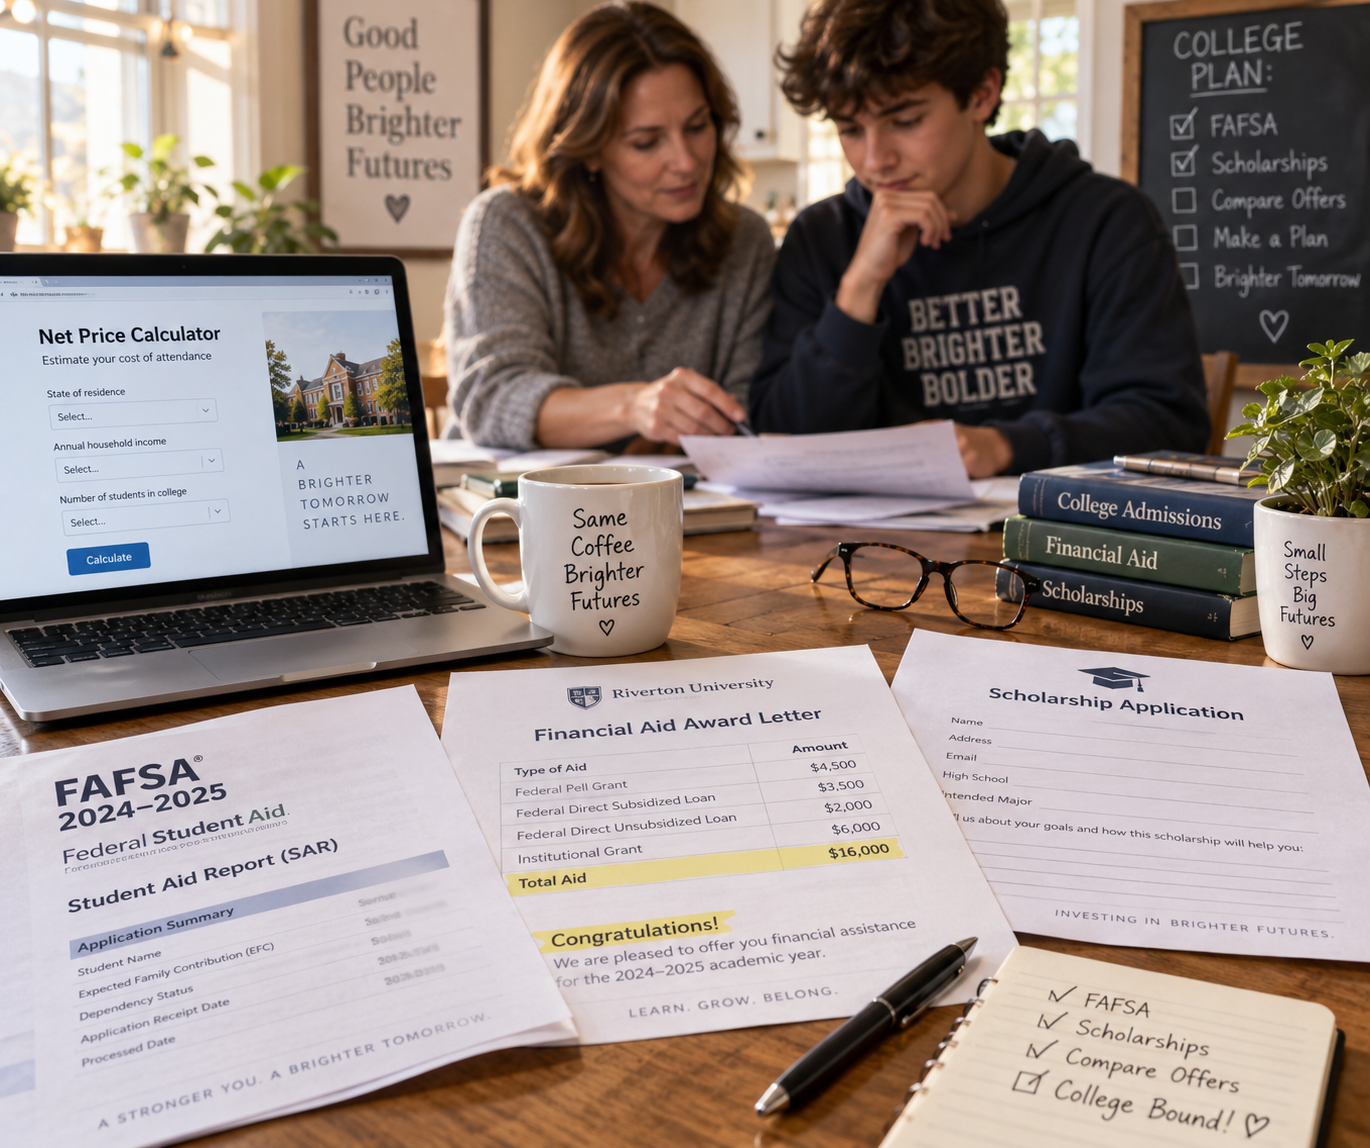
Some schools practice need-blind admission, meaning they do not consider your finances when deciding whether to admit you. Others are need-aware, which can matter at the margin for borderline applicants. A college's net price calculator, found on its financial aid page, gives a personalized estimate in about ten minutes. Run it before you fall in love with a school.
Grants and Scholarships: The Money You Keep
The Pell Grant remains the backbone of federal need-based aid, maxing out just under $7,400 per year for full-time undergraduates with sufficient need. State grants, institutional grants, and outside scholarships stack on top, while programs like SEOG and TEACH serve narrower populations.
On the scholarship side, the math favors volume and locality. National competitions draw tens of thousands of applicants; local Rotary clubs, professional associations, credit unions, and employer foundations often draw a few dozen. A student who applies to fifteen small local awards frequently does better than one chasing a single viral national prize. And remember that outside scholarships usually reduce the loan and work-study portions of your package first, not the grant portion — confirm the policy with each aid office.
Loans: Borrow Like an Adult
Federal direct subsidized loans do not accrue interest while you are enrolled at least half-time, during the grace period, or during deferment. Unsubsidized loans accrue from day one. Independent undergraduates can typically borrow more than dependents, and graduate borrowing is entirely unsubsidized with higher ceilings. Private loans may offer lower rates for borrowers with excellent credit and a cosigner, but they lack income-driven repayment, forgiveness programs, and generous death or disability discharge. Exhaust federal options first.
Deadlines, Verification, and the Cost of Waiting
Many state and institutional funds are awarded first-come, first-served until they run out. That is why a February priority deadline effectively beats a June federal one — by June, the best grants are often gone. Submit the FAFSA as soon as it opens for the coming year, then correct it later through the IRS direct data exchange if your estimates change.
Roughly one in four applicants gets flagged for verification, a random-seeming audit requiring tax transcripts and household documentation. Treat the request as urgent. A missing document can silently cancel your aid, and colleges rarely chase you twice.
Reading an Award Letter Without Getting Fooled
- Separate gift aid from self-help aid. Grants and scholarships are gifts; loans and work-study are things you repay or do.
- Subtract the loan portion from the package and compare what remains — that is your real discount.
- Check whether grants are renewable, and what GPA or credit-load conditions apply.
- Watch for front-loaded packages that quietly shrink after freshman year.
- Compare four-year costs, not just the first-year headline figure.
When the Offer Isn't Enough
Aid officers have discretion through professional judgment. If your family's finances changed — a layoff, divorce, medical bills, a closed business, a parent's death — you can appeal in writing with documentation. Address the letter to the financial aid office, not admissions. State the change, quantify it, and ask specifically what the school can do. Appeals are most successful in spring, before funds are committed, and are usually reviewed within two to four weeks. There is no penalty for asking, and many appeals produce additional aid.
Alternatives worth pricing: community college for two years, in-state public universities, honors colleges with automatic merit awards, and the American Opportunity Tax Credit, worth up to $2,500 per year against federal taxes.
The Takeaway
Financial aid rewards preparation. File early, file free, apply widely to small local scholarships, read every award letter line by line, and appeal when the numbers do not fit your reality. The families who save the most are rarely the ones with the highest incomes — they are the ones who treated the paperwork like a part-time job for three months.